CryptoMarket Making Fund-03 September Report
· 2026-10-05 17:50:38
Crypto Market‑Making Fund September Report
Risk Disclosure: This report is for reference only and does not constitute investment advice. Crypto assets are highly volatile and carry significant risk of principal loss.
I. Monthly Performance Review
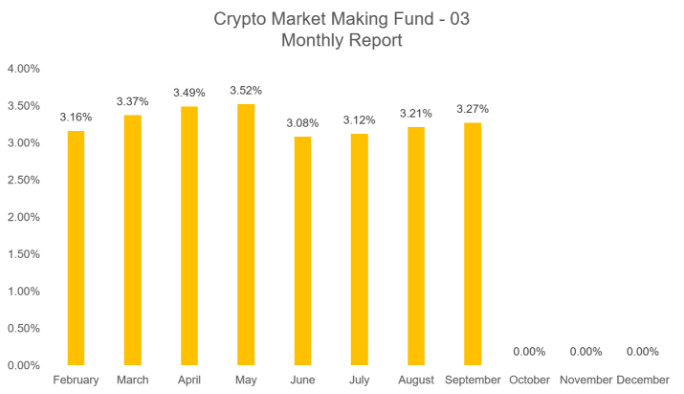
The crypto market‑making fund delivered a net return of +3.27% in September. Returns were generated from multiple sources including bid‑ask spreads, fee rebates and basis arbitrage. Net‑value volatility remained contained with a low maximum drawdown. Against a backdrop of choppy markets and range‑bound trading of major cryptocurrencies, the fund outperformed most directional single‑sided products.
In September, crypto markets were alternately driven by Federal Reserve policy expectations and spot‑ETF capital flows. Prices traded in wide ranges with limited trend persistence, yet intraday trading activity remained robust, creating favorable conditions for spread capture by market‑making strategies. Periodic arbitrage opportunities from basis and funding rates further boosted portfolio returns. Adhering to a neutral‑exposure framework, the fund strictly managed inventory risk without betting on directional price moves, earning steady returns by providing continuous liquidity.
II. Monthly Strategy Review
A. Core Execution: Dynamic Market‑Making Quoting
Bid‑ask spreads were dynamically adjusted according to market volatility. Spreads were widened amid high volatility to protect inventory, and tightened in calm markets to improve execution frequency. Trading activity focused on highly liquid pairs such as BTC and ETH, while exposure to small‑cap tokens was limited to avoid liquidity‑drying‑up risks.
B. Risk Control: Inventory‑Neutral Priority
Inventory bias was monitored continuously. Once one‑sided inventory built up, hedging and quoting adjustments were deployed to restore neutral positions, insulating net performance as much as possible from directional price swings. Returns do not rely on cryptocurrency price movements.
C. Return Enhancement: Supplementary Arbitrage
Low‑leverage exposure to futures‑spot basis and cross‑exchange price discrepancies served as supplementary return drivers to lift overall performance.
III. Current Market Outlook
Going forward, Federal Reserve policy expectations and spot‑ETF capital inflows and outflows will remain key market drivers. High‑volatility range‑bound trading is likely to persist, with sharp rallies and crashes possible at any time. For market‑making strategies: range‑bound conditions support spread‑based income; fast one‑sided trending markets will raise inventory‑management challenges and weigh on market‑making returns.
IV. October Strategy Outlook
A. Maintain the core neutral market‑making strategy. Concentrate on highly liquid major trading pairs and keep strict limits on small‑token positions.
B. Volatility‑threshold‑based risk management: Widen quotes and reduce single‑order sizes when volatility spikes, mitigating inventory losses caused by extreme price wicks.
C. Continue low‑risk futures‑spot and funding‑rate arbitrage for return enhancement, with overall leverage kept at conservative levels.
D. Risk‑control guardrails: Enforce inventory caps and daily loss‑cut triggers. Under extreme market conditions, scale back market‑making activity to preserve principal.
V. Summary
The +3.27% September result validates the effectiveness of neutral market‑making in range‑volatile markets. Market‑making funds are not designed for explosive returns; their strength lies in pursuing steady compound returns amid volatility. Should markets shift into strong bullish or bearish trending regimes, returns may moderate. Investors should understand strategy characteristics and maintain realistic return expectations.